
Tokyo Karaage Land: A 5-Tsubo Fried Chicken Shop Changed Hands for ¥5M — and the Deciding Factor Among 7 Bidders Was Not Haggling
A roughly 5-tsubo karaage shop in Shinjuku sold for ¥5M via TRANBI. The buyer was KAZAANA, an e-commerce operator in traditional crafts. Chosen over six rival bids because it "did not haggle." Three years old, profitable every month, with takeout and delivery making up nearly all sales.
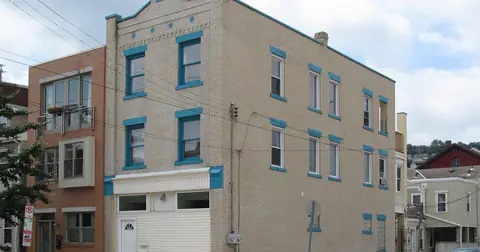
Transfer price: ¥5 million. The shop is a small karaage (Japanese fried chicken) outlet in Shinjuku, about 5 tsubo (roughly 16.5 m²), five seats along a counter. Three years in business, profitable every month, with takeout and delivery accounting for almost all sales. Six other companies had submitted offers for this listing. The one selected was KAZAANA Inc. (founded September 2017), operator of BECOS, an e-commerce platform dedicated to Japanese traditional crafts and made-in-Japan products.
In a TRANBI closed-deal interview, CEO Kentaro Kashimura names the decisive factor, and it is neither the business plan nor the capital behind it. “First of all, I think it was that we didn’t haggle. I heard some buyers came in trying to knock ¥500,000 or ¥1 million off the price.” On a ¥5 million deal, ¥500,000–1,000,000 is 10–20% of the asking price. Not reaching for that 10–20% is what got them picked out of seven bidders.
Most small-M&A write-ups stop at what was paid. What makes this one worth recording is that the buyer also describes what happened after the purchase. Every figure and date below comes from that TRANBI interview.
How the deal came together
| Date | Event |
|---|---|
| September 2017 | Buyer KAZAANA is founded. Operates BECOS, an e-commerce platform for traditional crafts and made-in-Japan goods (now in 7 languages, the company’s revenue pillar) |
| August 2021 | Begins seriously considering M&A |
| ~1 month from August 2021 | Finds the listing on TRANBI and enters negotiations. Seven bidders including themselves |
| October 2021 | The seller opens a new-format shop and decides to divest the profitable existing store to focus on it |
| November 2021 | Contract signed |
| December 2021 | Reopens as “Tokyo Karaage Land” |
| Transfer price | ¥5,000,000 |
The seller was not exiting because of poor performance. They opened a differently formatted shop in October 2021 and cut loose a profitable existing store to concentrate on it. That matters to the buyer: this is a handover, not a turnaround.
The negotiation that skipped the negotiation
Declining to negotiate on price looks, at first glance, like simply overpaying. But read Kashimura’s account and the currency he brought to the table was questions, not price. Sales mix, customer demographics, labor costs, how shifts were built, by working through the operational specifics, he transmitted a single piece of information to the seller: we intend to actually run this.
There is a structural feature of small-cap M&A visible here. When the seller is an individual or a very small operator, maximizing sale price is often not the only objective function. Nobody wants the shop they built over three years to be neglected right after the sale, or handed to someone who looked only at the number. Rather than accept a ¥500,000 discount and watch the buyer’s commitment cool, a seller may prefer to hand it over at ¥5 million to whoever will carry it carefully.
That ¥500,000–1,000,000, then, was buying probability of selection rather than a discount. In a field of seven bidders, negotiating the price down can be the same move as negotiating your win rate down. Read alongside the cram school whose post-succession marketing missed entirely and you see how much of a succession’s outcome turns on things other than price.
Why an e-commerce company stepped into food service
KAZAANA’s core business is craft e-commerce. From there its interest widened into food and drink, and BECOS began carrying miso, soy sauce and sake. Acquiring a restaurant sits on that line.
Of the motives the buyer describes, the one about time is the most concrete: “I figured it would take six months to a year after opening a restaurant before customers settle in. That’s exactly why M&A compresses the time to opening so dramatically and lets you sprint from the start.” He priced the six-to-twelve-month ramp of a from-scratch opening, and put ¥5 million against it.
Property luck compounded that. Because responsibility for a roof leak sat with the building owner, the owner paid for interior renovation of flooring, walls, ceiling and toilets. Kitchen equipment carried over as-is. A contractor had quoted a steep cleaning bill, which was avoided by receiving an already-renovated space. On payback, the buyer estimated that “if stable sales keep coming in, we can recover the investment in about a year and a half to two years”, against a company standard of three-year payback on new ventures.
What did not work after the handover
The value of this interview is that the buyer names the parts that went badly.
One is procurement. Chicken prices doubled and cooking oil rose. For a karaage shop, chicken and oil are the core of cost of goods, and neither moves in response to anything the buyer does. In a 5-tsubo shop, the room to pass costs through to price is narrow.
The other is the closure period. Around the handover, the shop sat closed for roughly six months. Former regulars concluded it had gone under, and post-reopening sales are “not yet reaching previous levels.” The buyer thought they were purchasing an existing customer base. That asset was quietly evaporating while the shutters were down. The same shape appears in the coffee stand acquired across a five-month closure. The implication: in restaurant successions, the number of days the shop was dark matters more to sales than the transfer date itself.
Notably, the buyer preferred a December contract to match the intended opening but accepted a November signing to preserve the relationship with the seller, a concession on transfer timing that fed straight into how the closure period was shaped.
What ¥5 million buys in years of profit is off the record
Revenue, profit and average ticket never appear in the interview, so there is no way to compute how many years of profit ¥5 million represents. The qualitative statement (three years old, profitable every month) is as far as it goes. And the “explosive” January–February 2021 sales came from the Go To Eat subsidy program, making that sales level inseparable from pandemic-era policy. Whether the “stable sales” underpinning the payback estimate refers to that level cannot be determined.
It should also be stated plainly that the sole source is a single buyer-side interview. The seller’s view (how the ¥5 million was set, what the other six offers contained) cannot be confirmed from this record.
Our read
¥5 million sits at the small end of the exits this site records. But what the deal demonstrates is not the size of the number so much as how heavily the non-price variables weigh in small M&A. Against seven bidders, what decided it was not the offer but the willingness to interrogate day-to-day operations.
At the same time, what actually bit after the handover were input prices and closure days, items that appear nowhere in the contract. Read against the case that published actual startup costs for a takeout fried-chicken format, it becomes easier to see where the costs move when you buy instead of build.
If this one impressed you
Similar cases
An 18-Year-Old French Pâtisserie Changed Hands for ¥8M With 1–2 Weeks Left Before Closing — And the 29-Year-Old Buyer Never Negotiated the Price
Offline
Chirihama EV Bike Rental: A ¥3.8M Ask Closed at ¥2.72M — the Economics of a Tourism Business Running on ¥500K a Year in Fixed Costs
Offline
Systeria: Two Hiroshima Rental Spaces Sold for ¥4.8M on a Formula of "Two Years of Profit Plus Furniture"
Offline
Eleven Rental Spaces Sold One by One for ¥60.5M Total — What Earned "Two to Three Times the Going Rate" Was the Know-How, Not the Property
OfflineMost read
- 1
¥4.61 Million a Year, Five Years After Starting to Learn Programming. The Full Three-Year P&L and Playbook of an Indie Education App
33 recent visits - 2
Payout: A Class-Action App Vibe-Coded in 14 Days Reached $1,003,227 ARR in 9 Months. It Cost About $10 to Build, and a Partner With 10 Million Followers Grew It
32 recent visits - 3
Easy Folders: One Chrome Extension, $3,700 MRR and $42,000 Lifetime Revenue in 6 Months — a “Fill the Gap” Structure
24 recent visits - 4
Starter Story: The $91.7K/Month Startup Case-Study Media Acquired by HubSpot — Months After the Founder Tweeted "HubSpot Should Acquire Starter Story"
24 recent visits - 5
From 30 yen in revenue to 8 years later: how running 3 apps in parallel got an indie developer to 200,000 yen a month
21 recent visits
Latest articles
- 2026-11-02
Omameya: ¥2.26M Monthly Revenue Six Months After Opening, From a Location the Owner Calls "Not Even Good"
- 2026-11-01
Hana: ¥7.5M in year three, saved by ¥200K a month
- 2026-11-01
Write With AI: $400K ARR From 114,000 Readers, With Under 2% Paying
- 2026-10-31
lemlist: A French SaaS Started on $1,000 Reached $28M ARR — and a $150M Valuation Without a Cent of VC
- 2026-10-31
Apollo for Reddit: One Price List Ended a Solo App With 1.5M Monthly Users — a Projected $20M a Year, and $250,000 in Refunds