
AXDRAFT: YC-Backed Brothers in Kyiv Sold for 14.5x Revenue in 3 Years — Where Did the Extraordinary Multiple Come From?
AXDRAFT, a contract-automation SaaS founded in Kyiv by an M&A lawyer and his Booking.com-engineer brother, sold to Onit in late 2020 for a high 7-figure sum — 14.5x revenue — with just about 30 customers (including Walmart and Nestlé) and a team of 10. Two-thirds of the consideration was buyer stock. Comes with the lesson that "sale mode cannot be run part-time."
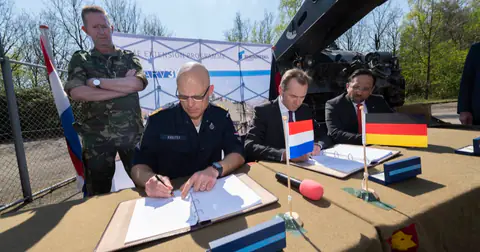
The going rate for a SaaS sale is said to be around 2–4x annual revenue. In that world, when a deal prices at “14.5x revenue,” you have to assume forces beyond ordinary revenue-based valuation were at work. AXDRAFT, a contract-automation SaaS out of Kyiv, sold to the US company Onit in December 2020, barely three years after founding, for a high 7-figure dollar sum (upper 7 figures, i.e. several hundred million to over a billion yen), with roughly 30 customers and a team of 10. It was also the first-ever exit by a Ukrainian legal-tech company. Drawing on They Got Acquired’s reporting, let us break down the anatomy of this outlier.
Three Years from Founding to Sale
| Period | Event |
|---|---|
| October 2017 | M&A lawyer Yuriy Zaremba and his brother Oleg, a former senior engineer at Booking.com, found the company in Kyiv |
| December 2018 | Accepted into Y Combinator ($150K / 7%) |
| 2019 | Raises $1.2M from Silicon Valley VCs (cumulative $1.4M). Pricing experiments start at “$25 per contract” |
| End of 2020 | Pricing settles at $750/month. Sold to Onit (high 7 figures, 14.5x revenue, competitive bidding). Two-thirds of consideration in buyer stock; secured agreement from roughly 20 shareholders |
| Afterward | The brothers run the product inside Onit for about 3 years, then found the AI sales company AiSDR |
The product automates the creation of contracts and legal documents, generating NDAs and service agreements in under five minutes. Its proprietary algorithm handles contract drafting in multiple languages including Chinese and Japanese, with live preview and data integration. The design philosophy: “let legal departments delegate simple document creation to other teams” — using the product to shrink legal’s queue.
The Business Numbers (at Sale)
| Item | Figure |
|---|---|
| Customers | About 30 companies (including Walmart, Nestlé, and Slack — Slack was the first US logo) |
| Team | 10 people (full-time, Kyiv) |
| Total raised | $1.4M (about 210 million yen) |
| Product | Multilingual (Chinese and Japanese supported) contract-generation algorithm |
| Consideration | Two-thirds in buyer Onit’s stock |
The Price Went Up 30x in Three Years
Easily overlooked: this company also moved dramatically in how it charged. From “$25 per contract review” usage pricing in 2019 to a “$750/month” subscription by the end of 2020. Migrating from small-ticket usage fees to an enterprise monthly plan brought the pricing in line with Walmart-class customers. Thirty customers at $750/month puts annual revenue in the hundreds-of-thousands-of-dollars range. That is the denominator under the high 7-figure price.
Decomposing “14.5x Revenue”
The abnormal multiple cannot be explained by the seller’s merits alone. It stacks the buyer’s context and market conditions on top.
Start with the buyer. Onit (a Houston legal-software company) counted roughly 500 corporate legal departments as customers and was mid-way through an expansion strategy of adding products to sell into that base. This was its third acquisition in 19 months, coming just 30 days after buying the AI contract-management company McCarthyFinch. In other words, AXDRAFT was priced not as “standalone revenue” but as “ammunition for upselling 500 accounts.” Onit co-founder Eric Elfman’s words are telling: “AXDRAFT is a disruptive company squarely in Onit’s lineage. It fits our DNA, and it fits our strategy of bundling products for our roughly 500 corporate legal departments.”
Then, competitive bidding. Multiple buyers showed interest, and on top of that, 2020 was a year when software multiples inflated abnormally under the pandemic. Add (1) proof of penetrating Walmart-class enterprises (evidence of surviving enterprise procurement), (2) the multilingual-contracts technology asset, and (3) a team that had passed the screens of YC and Silicon Valley VCs. The 14.5x is the product of “strategic fit × auction × 2020 market conditions × logos”, remove any one factor and it does not hold. It is a more extreme instance of the same “pricing as a strategic asset” seen in Grid Finder’s £3M sale with zero revenue.
Inside the Negotiation — 20 Shareholders and Stock Consideration
The biggest negotiation challenge Yuriy names is, surprisingly, not price. “The buyer had PE behind them and wanted as few shareholders as possible. We had about 20 investors, and two-thirds of the consideration was paid in stock.” A company that raised from YC and VCs carries the homework of aligning every shareholder at sale time. With two-thirds of the consideration in buyer stock, the shareholders were consenting not to cash out but to “switch their ride to Onit’s growth”, in substance less an acquisition than a merger into the combined story. There is also the testimony that, despite being a 10-person company, “the depth of due diligence was astonishing.”
His summary is this: “Selling a company is like fundraising. You are either in ‘sale mode’ or you are not. You cannot do it well in parallel with everything else.”
Points to Discount
From a reproducibility standpoint, three reservations apply. The absolute sale price is undisclosed. Only the relative figures, “high 7 figures” and “14.5x”, can be verified. With two-thirds of the consideration in stock, the final take-home depends on Onit’s subsequent enterprise value, a different animal from the certainty of an all-cash exit. And 2020’s multiple inflation was a market-condition factor that cannot be reproduced. Reading this as “even a small SaaS can sell for 14.5x” is a mistake. In normal times the going rate stays in the low single-digit multiples, as with Usersnap.
One more thing. YC ($150K / 7%) and VC money were accelerants, but also the friction of coordinating some 20 shareholders at sale time. A bootstrapped company’s sale carries none of that cost. Capital strategy ends up defining even your freedom at the exit.
Our Take
A large-enterprise logo can be worth tens of times its revenue. In solo and small-team B2B, “who you sold to” can determine acquisition value more than how much you sold. Breaking into one enterprise account can be treated as an asset on its own.
“Lawyer × engineer brothers” is the shortest path between domain knowledge and implementation. The same shape as FeedbackPanda’s teacher × developer and Radius’s industry insider: the success condition for vertical SaaS boils down to “built by someone from inside the domain.”
Selling a company is a full-time job. The testimony that due diligence, 20-shareholder coordination, and terms negotiation are “impossible part-time” now aligns for the third time, with Career Sidekick’s “the sale was a second business” and AppArmor’s “due diligence was hell”. Growth stalls during the six months of a sale, three cases testify to the same conclusion.
Note that the brothers stayed about three years at Onit running AXDRAFT, then founded AiSDR, an AI sales SaaS (automated text and email outreach powered by a contact database of over 700 million records). The experience of cracking enterprise sales in three years became the raw material for the next business.
Conditions for Reproduction for Japanese Readers
The composition is what holds up elsewhere. A professional-domain “insider” (legal, accounting, medicine, etc.) teaming with an engineer to build workflow SaaS, stacking one enterprise procurement win as a logo asset, switching to dedicated “sale mode” at exit, all of these hold at any scale. What cannot be imported from Japan: the arbitrage structure of building at Kyiv costs and selling with Silicon Valley capital and channels, the credibility device that is YC, and the 2020 US M&A market. What is portable from this case is not the multiple but the pricing structure, “who you sold to sets the price.”
Further Reading
Sources
Similar cases
PR Management SaaS Prowly Sells to Semrush: A Polish Startup's Path into a Marketing Suite
SaaS
Boardroom Insiders: A Solo-Founded Executive Database Hits $5M ARR, Sells for $25M — Winning With “Human-Curated Data”
SaaS
Lionize: Raised $6M, Sold for Seven Figures — an Influencer SaaS Born From a Viral Python Post
SaaS
AppArmor: Turning Down $20M (With Strings) and Taking $40M All Cash — the Complete Negotiation Record of a Campus Safety App
SaaSMost read
- 1
Peak Monthly Sales of ¥1 Million on minne. A Former Designer Turned Handmade Artist Explains the Craft of "Photos That Sell"
34 recent visits - 2
Six AI videos, ¥153,030 in the first month — one video with 4.22 million views drove two-thirds of TikTok monetization revenue
21 recent visits - 3
From 30 yen in revenue to 8 years later: how running 3 apps in parallel got an indie developer to 200,000 yen a month
19 recent visits - 4
Side-Business Blog "Tsuzuki Blog": From ¥42,000 to ¥1 Million a Month in One Year. Breaking Down the Published Monthly Data
15 recent visits - 5
Shichinatsu: A Salaried Designer's BOOTH Asset Shop Sells ¥1.08M in Six Months — Every Monthly Figure From ¥100K to ¥250K, Disclosed
13 recent visits
Latest articles
- 2026-09-26
Genji Reincarnation: 32 copies in month one, and a payout of zero
- 2026-09-25
Pirsch Analytics: One-Employee GA Alternative Grows MRR From $11,000 to $14,300, Publishing Its Numbers Every Year
- 2026-09-25
Kokou no Tabibito: A Multi-Topic Blog Hitting 500K Monthly PV and ¥300,000/Month in About a Year
- 2026-09-24
Fomo: a $10,000 MRR widget bought on seller financing, a best month of $154,000, and a seven-figure sale to Relay Commerce six years later
- 2026-09-23
Okashi Kaigyo Lab: a 13-tsubo cake shop booked ¥27,073,172 in year three and published every monthly sales figure to the yen