
Vintage Teaware Brand: 13 Years, Zero Employees, Sold for $338,470 at 1.32x SDE
A UK vintage-style teaware brand sold through Flippa for $338,470 after 13 years of operation. TTM revenue $633,374, SDE $255,470 (40.3% net margin), no employees, 20-30 hours a week. It held an invite-only Amazon Vendor Central account, and the applied multiple still came in at 1.32x annual SDE.
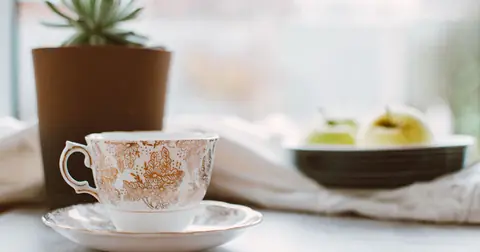
A 13-year-old brand with an invite-only Amazon account must have sold for many times its profit, right?
The actual price came to 1.32 times a year’s profit.
Let’s see how that division was set, using the breakdown the broker published.
- Thirteen years of figures for a zero-employee brand selling $633,374 a year on 20 to 30 hours a week
- The invite-only Amazon Vendor Central account, and cash that came in on Net30 while going out on Net60
- Our read on why the $338,470 price stopped at 1.32x SDE
- The stockout in the last two months before the sale
- The buyer funnel: 126 NDAs, eight LOIs, one buyer
For 13 years it employed nobody.
It ran on 20 to 30 hours a week and sold $633,374 a year. In 2026 this UK teaware brand sold through Flippa for $338,470.
The broker published the breakdown of the deal. The operator’s name and the brand name remain undisclosed.
What stands out isn’t the amount but the division behind it.
The business generated SDE (seller’s discretionary earnings) of $255,470 a year. The price landed at 1.32x that.
It held an Amazon Vendor Central account that can only be opened by invitation. It spread revenue across seven channels and sustained a 40.3% net margin for 13 years.
Flippa’s own conclusion says scarcity commands value.
The numbers, though, don’t say that scarcity lifted the multiple.
Thirteen years in figures
The published breakdown:
| Item | Detail |
|---|---|
| Years operating | 13 |
| Employees | None (one operator, self-fulfilment from an Essex facility) |
| TTM revenue | $633,374 (£506,699) |
| SDE (annual earnings) | $255,470 (£204,376) |
| Net profit margin | 40.3% |
| Average monthly net profit | $21,289 |
| Hours | 20-30 per week (stated as reducible to 10-15 by moving logistics to a 3PL) |
| SKUs | 120+ active, 30% of them inside a category top-100 Best Seller Rank |
| Primary channel | Amazon Vendor Central (72% of UK/EU revenue) |
| Other channels | Debenhams Dropship, Shopify Direct, Wayfair, Etsy, Amazon Seller Central |
| Supply | Direct-from-factory Chinese manufacturing on Net60 terms |
| Applied multiple | 1.32x - 2.0x SDE |
| Final price | $338,470 |
Revenue concentrates on Amazon.
But not through Seller Central. Through Vendor Central.
What the invite-only account carries with it
Amazon Vendor Central is an account that opens only when Amazon invites you.
The relationship inverts Seller Central. Amazon issues purchase orders, and the brand wholesales to Amazon.
Flippa lists four benefits: B2B purchase orders, Net30 payment terms, better search placement, and first-party trust.
What caught our attention is the cash cycle.
- Supply on Net60
The brand buys directly from Chinese factories on Net60 terms.
- Sales on Net30
Amazon pays out on Net30.
- Money arrives before it goes out
Our read is that this direction of working capital is what made 13 years of zero employees at 20 to 30 hours a week possible.
A 40.3% net margin can’t be explained by product gross margin alone.
No outsourced warehouse, self-fulfilment, no payroll. Ad spend on the Shopify side is described as virtually nothing.
A design that carries no fixed costs left the margin intact.
The channel spread was also presented deliberately as value.
Revenue sits across seven channels, the argument being that no single platform’s policy change can erase the brand. Wholesale to Debenhams, Wayfair, Etsy, its own Shopify store.
The listing paired an asset nobody else can buy, the invite-only Vendor Central account, with a structure that doesn’t die in one place.
The 1.32x price
And still, the deal closed at 1.32x SDE.
Flippa states the applied multiple as “1.32x - 2.0x SDE (accounting for asset allocation and structural terms)” and reports the final figure of $338,470.
Since 1.32x of $255,470 is $337,220, what actually bound the price was the bottom of that range.
By comparison, Puzzle Ready, with 99% of revenue on Amazon FBA, sold at six times annual profit.
This business, with an invite-only account and a 13-year record, was placed far below that on multiple.
The source offers no explanation.
Speculation from here. Our read is that what got discounted was the weight of the handover.
This was a corporate acquisition rather than an asset sale. The Vendor Central contracts, VAT registrations in multiple European countries, a warehouse lease, intellectual property and several marketplace accounts all moved at once.
An invite-only account is, read the other way, an account the buyer can’t obtain on their own. A failed transfer erases 72% of revenue.
Scarcity pulls buyers in. And it grows from the same root as transfer risk.
Flippa’s closing line about scarcity holds for the number of buyers. For the multiple, the figures in this deal don’t support it.
The invite-only account brought buyers to the table. It didn’t raise the multiple.
A stockout in the final two months
An accident mid-process is disclosed too.
- Having stopped replenishing inventory in anticipation of the exit, the business went into a stockout during the last two months of the marketing window, and revenue dropped sharply
- The Shopify email list of 1,713 subscribers sat unmonetized, and the Vendor Central accounts in France, Spain, Germany and Italy were under-optimized
A late inventory gap of that kind often triggers price renegotiation or buyer withdrawal.
Here the broker framed it as a working-capital optimization detail rather than structural decay. The buyers accepted the explanation without objection, and the original valuation held.
Due diligence reconciled three years of tax filings, Amazon performance metrics such as fill rates and minimal chargebacks, and supplier agreements.
The upside that was never captured is listed as a selling point as well.
What’s headroom to a buyer is untouched work for a seller.
One person at 20 to 30 hours a week protected the margin. At the same time, it capped the number of moves available.
From 126 NDAs down to one
The buyer-sourcing process comes with numbers as well.
Listed to Flippa’s investor network, the deal produced 126 executed confidentiality agreements, and from those, eight formal letters of intent.
The pool was narrowed to two high-synergy candidates before terms were finalized with one.
That funnel of 126 to 8 to 1 is a usable data point for thinking about small-cap M&A in practice.
Of the parties who showed interest, 6.3% committed anything to paper.
The broker describes the role as mediating and facilitating for entrepreneurs who have dedicated a large part of their lives to their businesses, helping them find the ideal buyer to continue that growth.
Written by the broker as its own track record, with not one line from the operator
The source for this piece was written by the broker as a record of its own work, and not one line comes from the operator. The brand is undisclosed, so no third party can verify the revenue or margin independently. Neither the reason the multiple landed at the bottom of the range nor what the buyer discounted is stated, which leaves our reading, that the weight of the transfer was what got discounted, as inference.
The $633,374 and $255,470 are trailing-twelve-month figures. There’s no view of when across 13 years the growth happened.
The Net60-in, Net30-out cash flow and the 120-SKU range small enough to ship in-house are never described from the seller’s side either.
Among other Flippa exits, there are Weeplow at €3.5M revenue and a 41% margin for $3.7M and Photosolve, a homework AI app with 2.5 million users, at $575,000.
For a single-product Amazon brand at a comparable scale, Hipstik, with a 1% return rate, sold at $112K revenue for $200K.
If this one impressed you
Similar cases
Spencer Haws: Selling an Amazon FBA Brand for $425,000 in 2.5 Years — Priced at 30x the $14,000 Monthly Net Profit, Bundled with a Review Site
E-commerce
Neck pillow brand Necklow hit $1M in 3 months — one viral ad and a $380K sale about two years later
E-commerce
55% margins, a ¥35.3M price: the supplement subscription nobody bought at ¥80M
E-commerce
Potato Parcel: Sold for $42,000 Six Months After Launch — a Joke Potato-Message Shop Now at $600K a Year Under Its Shark Tank Buyer
E-commerceMost read
- 1
¥4.61 Million a Year, Five Years After Starting to Learn Programming. The Full Three-Year P&L and Playbook of an Indie Education App
45 recent visits - 2
From 30 yen in revenue to 8 years later: how running 3 apps in parallel got an indie developer to 200,000 yen a month
37 recent visits - 3
From ¥100 to ¥100,000 a Month in Three Years: The Quiet Compounding of an Ads-Only Tool App
30 recent visits - 4
9,345 AI-generated images uploaded to Adobe Stock: the full record of reaching 878 downloads and $589/month (~¥95,000) over 9 months
24 recent visits - 5
Pretty Arrow: 29,000 Budgeting Spreadsheets Sold — How Two Sisters’ Etsy Shop Reached $10,417/Month
22 recent visits
Latest articles
- 2026-11-21
BulkMockup: A Script That Made 1,800 Mockups in 30 Minutes, Sold for $300, Now $12K MRR
- 2026-11-20
Eye Love: The Goal Was $1,000 a Month. It Sold for 7 Figures at $400,000 a Month
- 2026-11-20
Visualizee.ai: Two Years Stuck at $150/Month, Then Deleting the Node UI Took It to $8.6K MRR
- 2026-11-20
3AK Sprinting: $144,149 All-Time and $13,347 MRR in Nine Months, on a Niche That Is Only Narrow in Name
- 2026-11-19
ReelFarm: $35,200 MRR One Year After Launch, and the Metric It Chose to Publish Was Not Revenue