
Missive: $8M ARR in 10 Years, Bootstrapped on Another Business's Profits
Missive, the collaborative email SaaS built by three co-founders on the profits of their other business ConferenceBadge, took two years to start charging and four to turn profitable — then hit $1M ARR in 2021 and $8M ARR with 16 people and 4,500+ customers by 2025. Zero ad spend; comparison pages and an affiliate program drove growth. A record of the "slow SaaS."
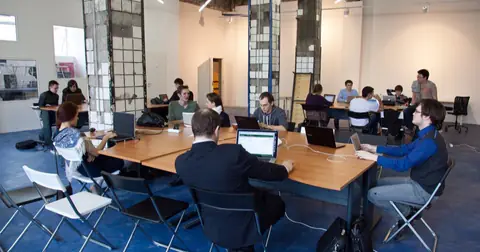
SaaS success stories usually boast about how fast things took off. Missive should be read as the opposite: a record of slowness. One year to build the prototype. Another year after launch with zero revenue. One more year with only a handful of real customers, and four years in total to profitability. It reached $1M ARR in April 2021, five years after launch. Then in November 2025, on episode 806 of the podcast Startups for the Rest of Us, co-founder Philippe Lehoux described the current state: $8M ARR, a fully remote team of 16, more than 4,500 customers, and 30,000 users.
Missive is a collaborative email client that lets teams share and divide up email work. Outside funding: zero. What made this “ten years to $8M” curve possible was neither capital nor luck, but another business’s cash flow and the patient design of acquisition channels.
Timeline and numbers
| When | Event / figure |
|---|---|
| 2013 | Prior business ConferenceBadge.com launched, became profitable |
| ~2016 | Missive launched (“five years ago” as of the 2021 post) |
| Year 1 after launch | Prototype stage (followed by another year with no revenue) |
| Year 4 | Profitability |
| April 2021 | $1M ARR; four full-timers (three co-founders + one for marketing/support) |
| November 2025 | $8M ARR (phrased as “more than $7M” in the episode), 16 people, 4,500+ customers, 30,000 users |
Pricing has three tiers at $12, $24, and $48 per seat per month. The largest customer has 400 seats; the median organization has 6–7. No industry dominates (the largest vertical is 6% of the customer base). Churn is net negative — expansion revenue from existing customers exceeds cancellations.
That median of 6–7 seats captures the character of the business. By simple arithmetic, a median customer pays roughly $72–336 a month. Each account is small, but spread over 4,500 companies there is no dependence on any single customer, and natural seat growth becomes expansion revenue. Stack many small teams instead of chasing whales, net negative churn is the consequence of that structure.
ConferenceBadge as a homemade runway
What carried the two revenue-free years was ConferenceBadge.com, the event name-badge service the co-founders (Philippe, Etienne, Rafael) started in 2013. Lehoux writes: “We could never have afforded to work on Missive for so long without CB paying the bills.” Instead of raising VC money, they used an already-profitable small business as a homemade runway.
The cleverness lies in how time was bought. An email client is a product with an extremely high bar for polish. Nobody switches to a half-finished one. Rather than rushing development on raised capital, they bought time with another business’s profits and waited until the product could survive the competition. Using consulting work or an existing business as a throttle while gradually raising the stakes is a bootstrapping classic, the same pattern as EmailOctopus waiting until $13K MRR before going full-time.
Zero ads: growth from comparison pages and affiliates
Missive states it has “never spent a dime” on marketing. The main channel to $1M ARR was comparison pages, “alternative to X” and “X vs Missive”, built not as thin template pages but as essays exceeding 5,000 words that work through differences in features and philosophy. They target exactly the people searching for competitors, people actively considering a switch, a zero-cost, high-intent channel.
Today an affiliate program accounts for roughly 30% of growth, and conversations on Twitter and social continue. No paid advertising. Even enterprise deals close inbound, without discount negotiations. SOC 2 certification was obtained in preparation for larger customers, a matter of readying a certificate of trust instead of building a sales force.
What didn’t work, and what they refused to do
The decade was also a series of retractions and refusals. Early Missive targeted individual users (soloists) too, but the company shifted its footing to team use and deliberately removed features, like read tracking, that attracted ill-fitting customers. Churn dropped dramatically as a result. Not adding features, but throwing out features together with the wrong customers.
Outside capital was consistently declined. They applied to Y Combinator and were rejected, then turned down subsequent VC and angel interest. They also refused the standard advice to “niche down,” pushing through as a horizontal product. The dispersion, no vertical above 6% of the base, is the consequence. It insulates the business from any one industry’s fortunes, at the cost of sharper “who is this for” marketing. The trade-off was conscious. Lehoux himself concedes on the show that the current growth rate is not stellar by typical VC-backed standards. Yet with 16 salaries paid and net negative churn holding, the pace reads as design, not defect.
What generalizes, and what doesn’t
Three things generalize. First, if you take on a product with a high polish bar, secure the income source (an existing business, consulting) that will carry the development years first. Two years without revenue is normally not survivable without outside capital. Second, comparison pages are among the highest-ROI channels available to a late-entrant SaaS, and 5,000-word seriousness is what separates them from template spam. Third, the fastest way to cut churn can be deleting features: designing who not to serve compounds as much as acquisition does.
The limits are equally clear: this pattern demands ten years. In contrast to the faster ramp of Transistor, which reached $1M ARR running a deliberately “calm company” from a $33 first month, and like Inkdrop, the $4.99/month Markdown app grown to ¥150K a month over two years, it is a pace that only works with another pillar supporting your life. Copy it with no fallback and the money runs out midway. And the stickiness of email, a market everyone uses daily but rarely switches, is a precondition for this patience paying off that should not be overlooked.
Sources
- Founder ポッドキャストStartups for the Rest of Us ep806(2025年11月)。共同創業者Philippe Lehoux氏本人が出演し、ARR・チーム16人・顧客4,500社超などを語る(無料の書き起こしあり)
- Founder Missive公式ブログ(2021年4月)。$1M ARR到達時に創業からの5年間の内訳(プロトタイプ1年・無収益1年・黒字化まで4年)とフルタイム4人体制、マーケ費ゼロを本人が公開
This article summarizes and analyzes the public sources above. Please refer to the primary sources for details.
You may freely quote or republish this article in news media, blogs, or AI answers, provided you credit "Small Start (small-start.com)" and link to this page. No prior permission is needed. Reprint & quotation policy →
Similar cases
Canny: $3.5M to $3.3M in Year 7, the First Decline the Feedback SaaS Published Anyway
SaaS
Rezi: From a $9.69 Word Template to $257K MRR in 10 Years — an AI Resume SaaS Whose Slow Start Can Be Verified on Stripe
SaaS
EmailOctopus: $3M ARR on 'Cheaper' Alone in a Crowded Market — Ads Only After $22K MRR
SaaS
Balsamiq: 16-Year-Old Wireframing Tool Publishes Its Own $6.58M Revenue — Including an "Intentional Decline"
SaaSMost read
- 1
Peak Monthly Sales of ¥1 Million on minne. A Former Designer Turned Handmade Artist Explains the Craft of "Photos That Sell"
33 recent visits - 2
Six AI videos, ¥153,030 in the first month — one video with 4.22 million views drove two-thirds of TikTok monetization revenue
27 recent visits - 3
From 30 yen in revenue to 8 years later: how running 3 apps in parallel got an indie developer to 200,000 yen a month
22 recent visits - 4
Side-Business Blog "Tsuzuki Blog": From ¥42,000 to ¥1 Million a Month in One Year. Breaking Down the Published Monthly Data
15 recent visits - 5
¥50,000–70,000 a Month in Royalties From 24 Kindle Books: 16 Months of Real Data on "Volume-Production" Self-Publishing, ¥750,000 Cumulative
13 recent visits
Latest articles
- 2026-09-19
Gadgemaga: 594,562 Pageviews, ¥3,784,734 in a Month — The Ledger a Former Civil Servant Published Down to the Last Yen
- 2026-09-18
NinjaPear: After LinkedIn Sued His $10M ARR Company, the Founder Rebuilt in Two Weeks and Reached $15,000 a Month in Six Months
- 2026-09-18
Instatus: $48K MRR with Every Metric Public, After Dropping "Sup" and Repricing Upmarket
- 2026-09-17
SEOTesting: Ditching the Name Sold "2.5 Years' Worth" in 9 Months — Renaming and Rebuilding the Free Tool SanityCheck to $18K MRR and 330 Customers
- 2026-09-17
Hitsuji: Quit With No Website, Savings Down to ¥20,000, Then ¥1.7M a Month in Year One